Revolut Clears First US Regulatory Hurdle for a National Bank Charter
 Admin
2 min read
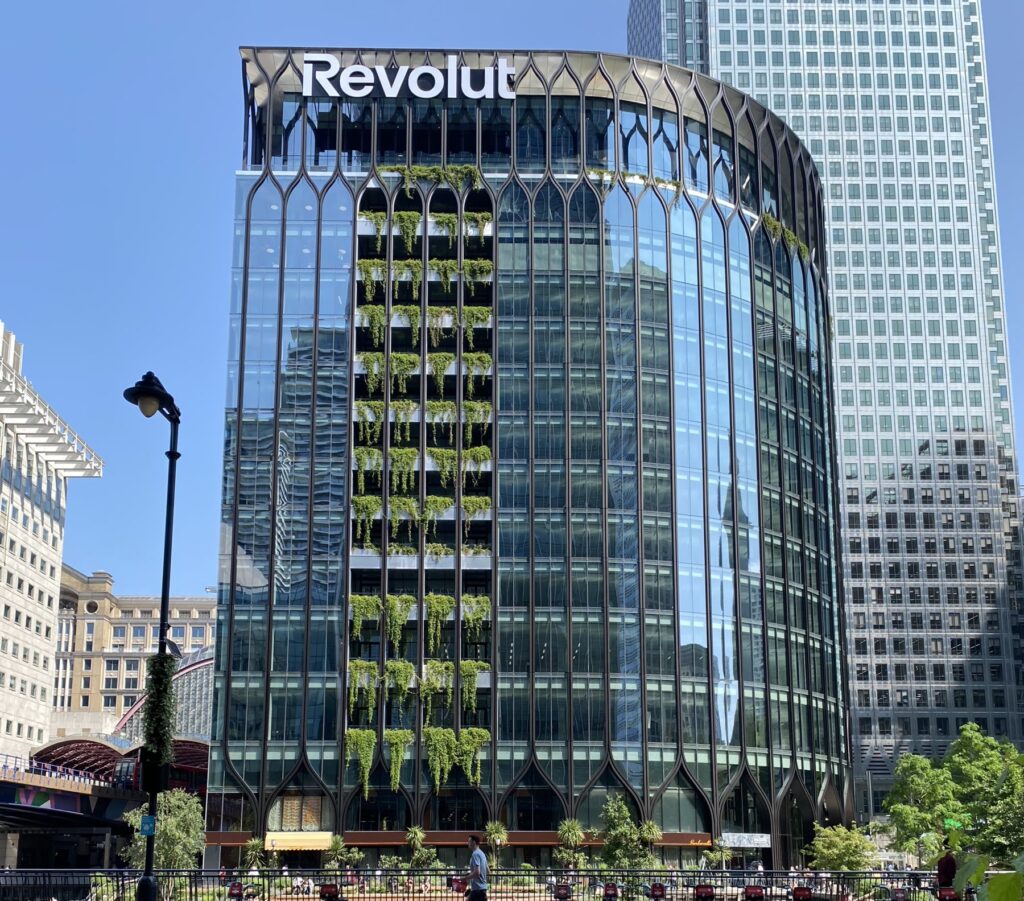
Boubloub, CC0 (public domain), via Wikimedia Commons
Image: Revolut’s head office at Canary Wharf, London. Photo by Boubloub, CC0 (public domain), via Wikimedia Commons.
The Office of the Comptroller of the Currency (OCC) granted Revolut preliminary conditional approval on 3 September 2026 to form Revolut Bank US, National Association, according to Crowdfund Insider and the OCC’s own published decision. It follows an application Revolut filed in March 2026, when this site reported the company had applied for a US bank charter and named Cetin Duransoy as its US chief executive.
Conditional approval is not the same as a licence to open. Revolut must still satisfy further OCC conditions, secure deposit insurance from the Federal Deposit Insurance Corporation, obtain Federal Reserve approval, and receive the OCC’s final authorisation before Revolut Bank US can begin operating. The preliminary approval explicitly excludes Revolut’s proposed retail foreign-exchange business, which needs separate supervisory sign-off.
What Revolut Said
Cetin Duransoy said regulators had conducted a review that was “both thorough and relatively fast,” according to Crowdfund Insider, and that the company remains on schedule to open in the first half of 2027. Revolut has proposed basing the bank in Stamford, Connecticut, with initial capital of around $95 million and roughly 160 staff at launch. Planned products include checking accounts, instalment loans, credit cards, foreign-exchange services and, subject to further approval, stablecoin and digital-asset features.
Why a Bank Charter Matters to Revolut
Revolut currently offers US customers services through partner banks. A national charter would let it hold deposits, make loans and issue credit directly, ending that reliance and, in principle, giving it more control over costs and product design in its largest potential market.
Part of a Wider Charter Boom
Revolut’s progress sits inside a broader surge in bank-charter activity. Banking Dive reported in January 2026 that the OCC received 18 de novo charter applications in 2025 alone — matching the total from the previous four years combined — with Comptroller Jonathan Gould describing the influx as “a return to the norm” for the agency. Klaros Group co-founder Michele Alt was quoted saying fintechs have “gained a lot of ground” in market share and product innovation, prompting more of them to seek their own charters rather than rely on sponsor banks.
Stablecoin issuer Circle received final OCC approval in July 2026 for a separate type of charter — a national trust bank permitting custody services but not deposits or lending — illustrating that fintechs are pursuing several different kinds of charter depending on what they actually plan to do.
What to Watch Next
Revolut’s next steps are FDIC and Federal Reserve approval, followed by the OCC’s final authorisation — each a real point where the process could stall or add conditions, as it has for other applicants industry-wide.