ECB Raises Rates for Second Time This Year as Iran War Pushes Eurozone Inflation to Three-Year High
 Admin
2 min read
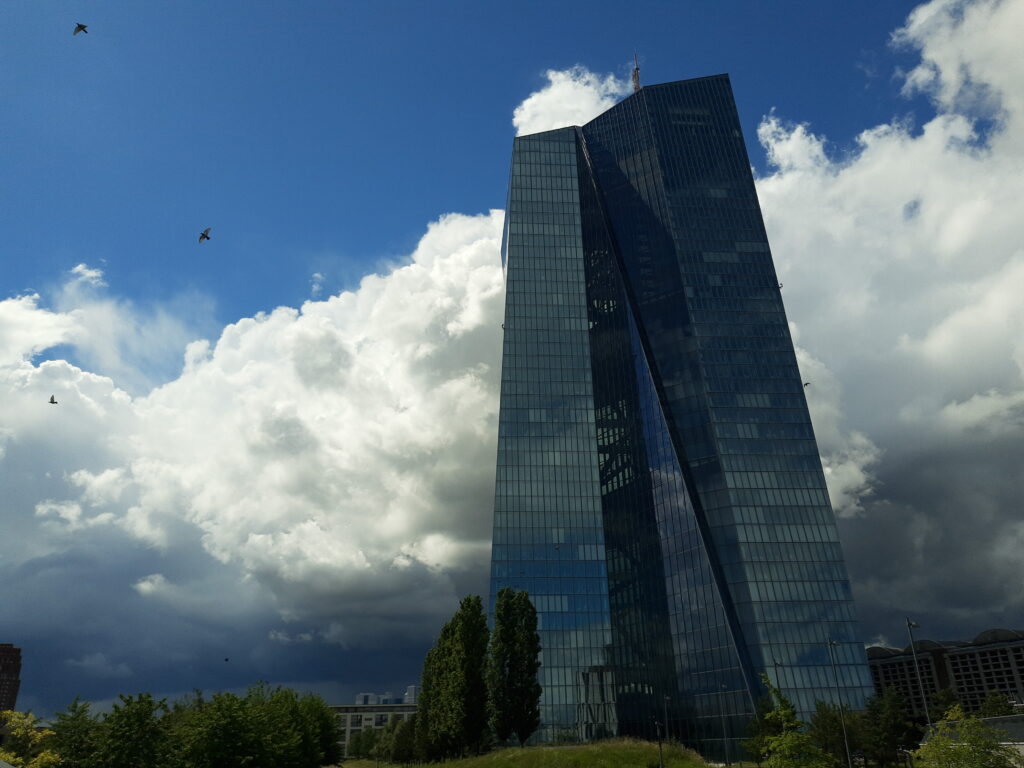
The European Central Bank raised its deposit rate by a quarter point to 2.5% on 10 September, with the main refinancing rate rising to 2.65%, according to a report by Trading Economics. It was the ECB’s second rate rise this year, and came as eurozone inflation accelerated to 3.3% in August — its highest level in three years and well above the central bank’s 2% target.
Energy Costs Driving the Move
The ECB linked the decision directly to the conflict involving Iran, which has driven up crude and gas prices across the bloc for months. Disruption to shipping through the Strait of Hormuz has been a central factor in the wider energy shock, though the bank noted few signs yet of the kind of secondary effects — energy costs feeding into broader wage and price setting — that would make the inflation problem harder to reverse.
ECB President Christine Lagarde said “risks to growth are tilted to the downside, while inflation risks are currently tilted to the upside,” and stressed that further decisions would be made on a meeting-by-meeting basis rather than on a preset path.
A Difficult Balancing Act
The ECB’s dilemma is a familiar one for central banks this year: energy-driven inflation is not the kind that a rate rise can directly fix, since it stems from supply disruption abroad rather than excess demand at home. Raising rates anyway signals that the bank is more worried about inflation expectations becoming unanchored than about the near-term drag higher borrowing costs place on growth.
The bank’s own 2026 inflation forecast has been maintained at 3.0%, suggesting policymakers expect price pressure to ease only gradually rather than reverse quickly, even with rates higher.
Why It Matters Beyond the Eurozone
A second ECB rate rise this year adds to a pattern seen at other major central banks in September, with both the U.S. Federal Reserve and the Bank of England also weighing, or already responding to, the same Iran-conflict energy shock. For eurozone borrowers, higher ECB rates mean higher costs on variable-rate mortgages and business loans; for savers, better returns on euro-denominated deposits. For the wider currency bloc, it also signals that the ECB currently views the energy shock as serious enough to accept some growth drag in order to keep inflation expectations under control.